Technological Prisms: A Configurational Analysis of Robo-Advice Beliefs, Adoption, and Incumbent Adaptation in the Financial Advice Sector
Explore the impact of robo-advice on financial services, examining beliefs, adoption patterns, and incumbent adaptations through configurational analysis.
Drawdown Betas - Measuring Drawdown Risk and Portfolio Optimization
Explore drawdown risk measurement and portfolio optimization techniques with Stan Uryasev. Learn about drawdown betas and their application in quantitative wealth management strategies.
Tontines as a Tool for Wealth Management
Explore tontines as a wealth management strategy, examining their historical context, modern applications, and potential benefits for financial planning and retirement income.
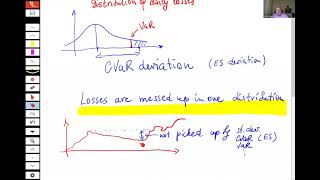
Drawdown Beta and Portfolio Optimization
Explore a new dynamic portfolio performance risk measure, Expected Regret of Drawdown (ERoD), and its implications for portfolio optimization, risk management, and the Capital Asset Pricing Model.
Machine Learning, Financial Stress and Investment Behaviours
Explore machine learning applications in analyzing financial stress and investment behaviors, focusing on quantitative finance techniques and real-world implications.
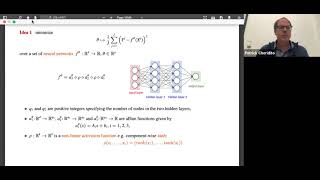
Assessing Asset-Liability Risk and the Numerical Approximation of Conditional Expectations
Explore asset-liability risk assessment and numerical approximation techniques for conditional expectations in quantitative finance, enhancing risk management skills.
Climate and Sustainable Finance
Explore the intersection of finance and sustainability, examining innovative approaches to address climate change through financial mechanisms and investments.
A Stochastic Control Approach to Defined Contribution Plan Decumulation - The Nastiest, Hardest Problem in Finance
Explore stochastic control methods for optimizing retirement fund withdrawals, addressing complex financial challenges in defined contribution plan decumulation strategies.
Portfolio Selection Under Ambiguity and Under-Diversification Puzzles
Explore portfolio selection strategies addressing ambiguity and under-diversification, examining innovative approaches to optimize investment decisions and manage risk in wealth management.
Analyzing Investment Behaviours and Their Impact on Investment Results
Explore how investor behaviors influence investment outcomes, examining quantitative methods for wealth management and their practical applications in financial decision-making.
Algorithm Aversion: Theory and Evidence from Robo-Advice
Explore the phenomenon of algorithm aversion in robo-advice, examining theoretical foundations and empirical evidence to understand its impact on wealth management and financial decision-making.
Regime-Aware Portfolio Models
Explore advanced quantitative methods for wealth management, focusing on regime-aware portfolio models to enhance investment strategies and decision-making.
Learning From Transaction-Level Investment Account Data
Explore machine learning techniques for analyzing transaction-level investment data, focusing on practical applications in wealth management and financial decision-making.
Software Architecture in Banking and Finance 2021 - Bernd Rücker, Co-Founder, Camunda
Explore microservices architecture in banking: benefits, implementation strategies, and orchestration techniques for successful business processes and workflows in the digital era.
Microsoft Cloud for Financial Services - Human-Centered Digital Banking Solution
Reimagining retail banking with digital-first experiences and personalized advice, leveraging Microsoft Cloud for Financial Services and partners to provide anytime, anywhere banking with human-centered solutions.
Securing Endpoints with Defender and Microsoft Endpoint Manager - Ask the Experts
Expert insights on enhancing endpoint security using Microsoft Defender and Endpoint Manager. Learn monitoring, analysis, vulnerability detection, and real-time compliance strategies from product managers and engineers.
WooCommerce Settings and Payments Gateway Set Up Tutorial 2023 - Stripe and PayPal Step by Step
Step-by-step guide for setting up WooCommerce, configuring settings, and integrating Stripe and PayPal payment gateways. Covers essential aspects of e-commerce setup for online businesses.
Learning to Simulate Tail Risk Scenarios
Explore advanced techniques for simulating extreme financial events, focusing on tail risk scenarios and their impact on quantitative finance strategies.
Systemic Fragility in Decentralized Markets
Explore systemic fragility in decentralized markets, examining liquidation data, collateral tokens, and decentralized exchanges to understand their impact on market stability.
The End Is Near? Prices and Reserves as Predictors of Exploratory Resources Exhaustion
Explore the relationship between prices, reserves, and resource exhaustion in this seminar by Dr. Peter Tankov, examining predictors of exploratory resources depletion.
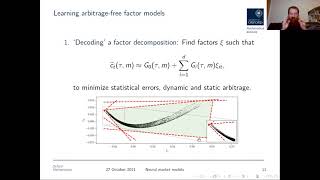
Arbitrage-Free Neural-SDE Market Models
Explore neural-SDE market models for arbitrage-free pricing, combining machine learning with stochastic differential equations in quantitative finance.