
Risk and Financial Crises - Probability Theory in Financial Markets
Explore probability theory in financial crises context, covering expected value, variance, covariance, and regression analysis. Learn about risk decomposition and the limitations of normal distribution assumptions in finance.

The Great Recession - International Economic Institutions
Explore the Great Recession's causes, from misused financial tools to government policy mistakes. Analyze risk management, mortgage markets, and economic decision-making in this insightful examination of the 2008 financial crisis.
An Open Source Architecture for Modernizing Market Risk Management
Modernizing market risk management with open-source architecture: scaling calculations, accelerating model deployment, and improving risk management through hybrid cloud, DevSecOps, and event-driven architecture.
Risk Management of Option Books with Arbitrage-Free Neural-SDE Market Models
Explore advanced risk management techniques for option books using arbitrage-free neural-SDE market models, covering nonparametric modeling, inference, and hedging strategies with real-world applications.
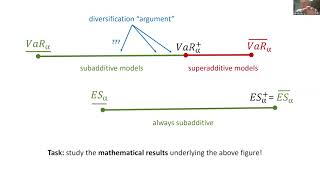
Dependence, Uncertainty, and Risk - Prof. Paul Embrechts
Explore quantitative risk management through extremal bounds for risk measures, focusing on uncertainty in interdependence between risk factors and its impact on portfolio analysis.