Option Pricing Bottom Up and Top Down
Explore option pricing methodologies, from classic bottom-up to innovative top-down approaches, analyzing their strengths and applications in financial markets.
Become an Options Trading Pro - Options Trading for Beginners
Comprehensive guide to options trading, covering basics to advanced strategies. Learn calls, puts, spreads, volatility, and risk management for successful trading.

Option Learning Series
Comprehensive equity option trading series covering basics to advanced strategies, including market fundamentals, pricing models, Greeks, and various trading techniques.
Super-Hedging Prices in Financial Markets with Transaction Costs
Poznaj strategie super-hedgingu na rynkach finansowych z kosztami transakcyjnymi. Zgłęb matematyczne podejście do wyceny i zabezpieczania inwestycji.
Deep Learning Volatility - Blanka Horvath, Kings College London
Explore deep learning for option pricing and calibration, including neural network perspectives, rough volatility, and model recognition in financial mathematics.
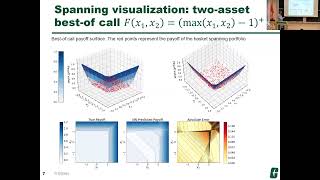
Spanning Multi-Asset Payoffs with ReLUs
Explore innovative techniques for spanning multi-asset payoffs using Rectified Linear Units (ReLUs) in mathematical finance, enhancing portfolio optimization strategies.
Deep Solver for Jumps in Backward Stochastic Differential Equations - Lecture
Innovative extension of deep solver for FBSDEs with jumps, using neural networks to tackle high-dimensional problems in option pricing and counterparty credit risk.
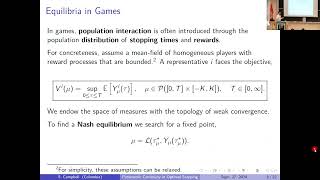
Parametric Continuity in Problems of Optimal Stopping with Applications to American Options and Stopping Games
Explore parametric continuity in optimal stopping problems, focusing on applications to American options and stopping games. Gain insights from cutting-edge research in mathematical finance.
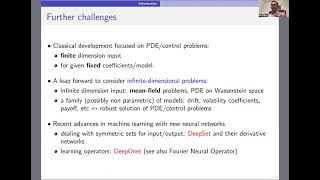
DeepSet and Derivative Networks for Solving Symmetric Problems
Explore DeepSet networks for solving symmetric problems in high-dimensional PDEs and control, with applications in finance and mean-field control. Learn about their advantages and performance in various scenarios.
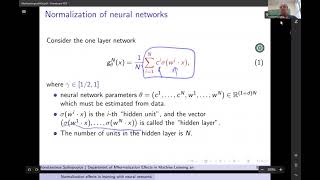
Normalization Effects on Neural Networks: Generalization and High-Dimensional Applications - SIAM FME Talk
Exploring neural network performance, normalization effects, and high-dimensional PDE solving using deep learning. Insights on generalization properties and applications in mathematical finance.