Equal Risk Option Pricing with Deep Reinforcement Learning
Explore innovative option pricing using deep reinforcement learning, focusing on equal risk approaches, hedging strategies, and market dynamics. Gain insights into advanced quantitative finance techniques.
Arbitrage-Free Yield Curve and Bond Price Forecasting by Deep Neural Networks
Explore deep neural networks for arbitrage-free yield curve and bond price forecasting, enhancing quantitative finance strategies and market predictions.
Risk-Aware Reinforcement Learning for Finance
Explore risk-aware reinforcement learning in finance, covering time-consistent approaches and applications to financial modeling. Learn from expert Sebastian Jaimungal about innovative strategies beyond traditional RL methods.
Quantitative Finance - Toward A General Framework for Modelling Roll-Over Risk
Explore quantitative finance and reinforcement learning in this SIAM talk series, featuring discussions on roll-over risk modeling and continuous-time episodic RL with linear-convex models.
Derivatives Analytics with Python & Numpy
Explore financial derivatives analytics using Python and NumPy, focusing on efficient implementation and practical applications in quantitative finance.
Probabilistic Programming in Python
Learn probabilistic programming in Python using PyMC3 for flexible statistical modeling, automated parameter estimation, and uncertainty quantification in data science and scientific research.

ME3255 - Evaluating a NYSE Monte Carlo Model
Evaluate a NYSE Monte Carlo model using advanced statistical techniques. Gain insights into financial modeling and risk assessment for stock market analysis.
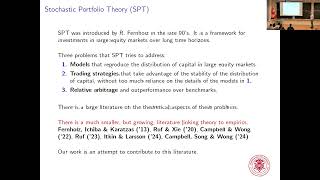
Large-Scale Dynamics of Equity Markets of Variable Size - An Empirical Analysis
Delve into empirical analysis of equity market dynamics, exploring size variations and their impact on large-scale financial systems through advanced quantitative methods.
Building Your Own Trading Bot in F#
Aprenda a criar um bot de negociação em F# e traduza estratégias de trading em código funcional correto.
Introduction to SciPhy Reinforcement Learning - Part 1
Explore SciPhy RL: a neural network-based method for solving stochastic optimal control problems in continuous time, with applications and high-dimensional examples.