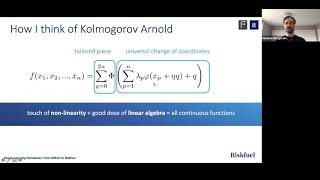
Deeply Learning Derivatives - From Hilbert to Riskfuel
Explore advanced derivatives pricing using deep learning, from Hilbert's 13th problem to modern neural networks for valuing high-dimensional contingent claims in quantitative finance.
Simulated Greeks for American Options
Explore simulated Greeks for American options, covering hedging strategies, state variables, and regression techniques. Compare with European options for comprehensive understanding.
Semi-Parametric Pricing and Hedging of Barrier-Style Claims on Price and Volatility
Explore advanced techniques in quantitative finance for pricing and hedging barrier-style claims, focusing on semi-parametric approaches and their applications in complex financial models.
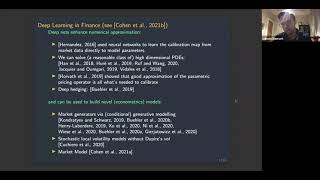
Neural SDEs, Deep Learning and Stochastic Control
Explore neural SDEs, deep learning, and stochastic control in finance, covering optimal transport, neural networks, calibration, and simulations with practical applications.
Drawdown Beta and Portfolio Optimization
Explore a new dynamic portfolio performance risk measure, Expected Regret of Drawdown (ERoD), and its implications for portfolio optimization, risk management, and the Capital Asset Pricing Model.
Machine Learning, Financial Stress and Investment Behaviours
Explore machine learning applications in analyzing financial stress and investment behaviors, focusing on quantitative finance techniques and real-world implications.
Assessing Asset-Liability Risk and the Numerical Approximation of Conditional Expectations
Explore asset-liability risk assessment and numerical approximation techniques for conditional expectations in quantitative finance, enhancing risk management skills.
Learning to Simulate Tail Risk Scenarios
Explore advanced techniques for simulating extreme financial events, focusing on tail risk scenarios and their impact on quantitative finance strategies.
The End Is Near? Prices and Reserves as Predictors of Exploratory Resources Exhaustion
Explore the relationship between prices, reserves, and resource exhaustion in this seminar by Dr. Peter Tankov, examining predictors of exploratory resources depletion.
Arbitrage-Free Neural-SDE Market Models
Explore neural-SDE market models for arbitrage-free pricing, combining machine learning with stochastic differential equations in quantitative finance.
Risk Management of Option Books with Arbitrage-Free Neural-SDE Market Models
Explore advanced risk management techniques for option books using arbitrage-free neural-SDE market models, covering nonparametric modeling, inference, and hedging strategies with real-world applications.
Towards Data-Driven Equal Risk Pricing and Hedging of Financial Derivatives
Explore data-driven approaches for equal risk pricing and hedging of financial derivatives, focusing on innovative methods in quantitative finance.
Robust Distortion Risk Measures in Quantitative Finance
Explore robust distortion risk measures in quantitative finance, examining their applications and implications for risk assessment and management strategies.
Statistical Prediction of Trading Strategies in Electronic Markets
Explore statistical methods for predicting trading strategies in electronic markets, focusing on advanced techniques and their applications in quantitative finance.
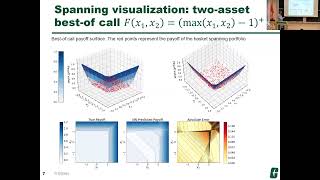
Spanning Multi-Asset Payoffs with ReLUs
Explore innovative techniques for spanning multi-asset payoffs using Rectified Linear Units (ReLUs) in mathematical finance, enhancing portfolio optimization strategies.
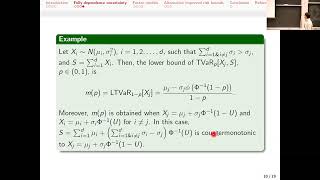
Risk Bounds for the Marginal Expected Shortfall Under Dependence Uncertainty
Explore risk bounds for marginal expected shortfall under dependence uncertainty, focusing on advanced mathematical concepts and financial risk analysis techniques.
Deep XVA - Efficient Derivative Valuation for Risk Management
Explore efficient XVA calculation using deep learning, GPU computation, and AAD for computationally intensive finance models.
Revolutionizing Financial Data Integration - The OpenBB Edge
Discover how OpenBB democratizes quantitative finance through open-source tools, enabling comprehensive financial data integration and analysis for organizations of all sizes.
Portfolio Choice for Exponential Investors in Mean-Reverting Markets
Explore portfolio optimization for exponential utility investors in mean-reverting asset classes. Learn about optimal strategies, equivalent safe rates, and the impact of drift on performance in various market scenarios.
A Simple Microstructural Explanation of the Concavity of Price Impact
Explore a microstructural model explaining price impact concavity in financial markets, with insights on order flow, fundamental pricing, and meta-order execution dynamics.

Unlocking Your Freedom - Exploring the Boundaries and Possibilities of Math in Finance
Explore the innovative applications of mathematics in finance, unlocking new possibilities and expanding boundaries for financial analysis and decision-making.