Schatten Properties for Noncommutative Martingale Paraproduct
Explore Schatten class memberships of d-adic martingale paraproducts in semi-commutative settings and characterize Sp-norms using transference methods.
From the Littlewood-Paley-Stein Inequality to the Burkholder-Gundy Inequality
Explore optimal constants in Littlewood-Paley-Stein inequality through special diffusion semi-group construction, relating G-function to martingale square function in various cases.
On the Positivity of Meijer G-Functions
Explore positivity of Meijer G-functions, logarithmic infinite divisibility, and quasi infinite divisibility. Extend findings to Fox H-Functions.
Random Lattices as Sphere Packings
Explore lattice-sum functions and their applications in sphere packing density, including Siegel's mean value theorem and recent advancements in optimal packing bounds.
When Your Big Data Seems Too Small: Accurate Inferences Beyond the Empirical Distribution - Part 2
Explore advanced techniques for accurate distribution inferences with limited data. Learn to de-noise empirical distributions, estimate population spectra, and recover low-rank matrix approximations.
Spontaneous Stochasticity in Multi-Scale Dynamics
Explore spontaneous stochasticity in multi-scale dynamics, focusing on turbulence models and the formalization of stochastic solutions using renormalization-group operator attractors.
Universality for Random Polynomials: Framework and Applications
Explore universality in random polynomials, its applications to root distribution, and solutions to classical problems. Learn about a general framework for establishing universality properties.

Monte Carlo Methods for NYSE Stock Predictions - ME3255
Explore Monte Carlo methods for predicting NYSE stock movements. Learn statistical techniques to analyze market trends and make informed investment decisions.

ME3255 - Quantitative Descriptions on Monte Carlo Models
Explore Monte Carlo models through quantitative descriptions, enhancing understanding of statistical simulation techniques and their applications in engineering and science.

ME3255 - Moore's Law and Monte Carlo Methods
Explore Moore's law and Monte Carlo methods in computational mechanics, gaining insights into technological advancements and simulation techniques for engineering applications.
GCI Speaker Series: Probability, Statistics, and Philosophical Questions - Aubrey Clayton
Explore probability, statistics, and fallacies with Dr. Aubrey Clayton in this thought-provoking speaker series on economic data analysis and philosophical implications.
Where Do Random Trees Grow Leaves - A Study of Binary Tree Growth Dynamics
Explore the growth patterns of random binary trees, focusing on leaf addition dynamics and fractal properties in tree structures.
Global Solutions to Quadratic Systems of Stochastic Reaction-Diffusion
Explorez les solutions globales des systèmes quadratiques de réaction-diffusion stochastique en dimension deux, avec un accent sur les perturbations à quatre espèces.
Particle Approximation of the Doubly Parabolic Keller-Segel Equation in the Plane
Explore particle approximation of the parabolic-parabolic Keller-Segel system in the plane, focusing on stochastic particle systems, tightness, and weak solutions for small sensitivity parameters.
Random Models on Regularity-Integrability Structures
Explore a simplified proof of the BPHZ theorem using extended regularity structures with integrability exponents, advancing the study of singular stochastic partial differential equations.
Regularity Structures for Quasilinear Singular SPDEs
Explore regularity structures for analyzing semilinear and quasilinear parabolic singular stochastic PDEs, suitable for beginners and experts alike.
Outliers of Perturbations of Banded Toeplitz Matrices
Explore outlier eigenvalues of perturbed banded Toeplitz matrices, focusing on their behavior in regions outside the limiting spectral distribution's support as matrix size increases.
Zeros of Random Power Series with Stationary Gaussian Coefficients
Explore zeros of random power series with stationary Gaussian coefficients, comparing to i.i.d. case and analyzing expected zero count in disks as radius approaches convergence.
Dunkl Operators, Random Matrices and Hurwitz Numbers
Explore probabilistic aspects of Dunkl operators, including radial Dunkl processes, reflected Brownian motion in Weyl chambers, and connections to Hurwitz numbers and generalized Bessel functions.
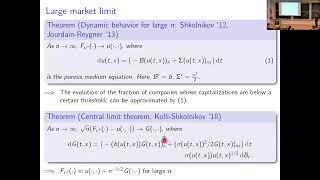
From Rank-Based Models with Common Noise to Pathwise Entropy Solutions of SPDEs
Explore rank-based models with common noise and their connection to pathwise entropy solutions of SPDEs. Gain insights into advanced mathematical concepts and their applications.
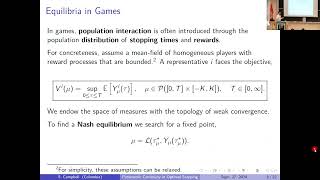
Parametric Continuity in Problems of Optimal Stopping with Applications to American Options and Stopping Games
Explore parametric continuity in optimal stopping problems, focusing on applications to American options and stopping games. Gain insights from cutting-edge research in mathematical finance.