
Tradier API - Stock and Option Trading with Python - First Impressions
Explore Tradier's API for commission-free stock and option trading using Python. Learn about historical data, real-time streaming, complex orders, and multi-legged options.
Testing Stock Trading Strategies with Ichimoku Analysis
Learn to test stock trading strategies using Python, focusing on Ichimoku analysis with real-time data, customizable charts, and performance evaluation techniques.
On Modeling Investors in Simulated Markets
Explore multi-agent market simulations, from market replay to advanced AI-driven models. Learn about trading agent design, market impact analysis, and applications in financial research.
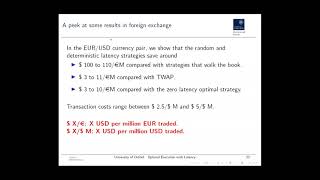
Optimal Execution with Stochastic and Deterministic Delay - SIAM FME Virtual Talk
Explore optimal execution strategies in financial markets with random delays, considering price impact and transaction costs. Learn about innovative impulse control models and their practical applications.
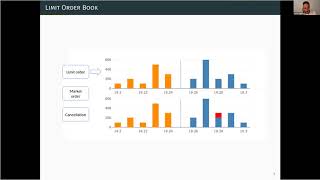
Detecting Spoofing Strategies in High Frequency Trading
Exploring detection methods for spoofing strategies in high-frequency trading, focusing on volume imbalance impact and optimization models to identify manipulative behaviors in limit order books.
Statistical Prediction of Trading Strategies in Electronic Markets
Explore statistical methods for predicting trading strategies in electronic markets, focusing on advanced techniques and their applications in quantitative finance.

Monte Carlo Methods for NYSE Stock Predictions - ME3255
Explore Monte Carlo methods for predicting NYSE stock movements. Learn statistical techniques to analyze market trends and make informed investment decisions.

Fear and Greed Revisited - Backtesting a VIX Spike Trading Strategy with Python
Backtest a VIX spike trading strategy using Python, exploring buying opportunities during market fear and comparing selling strategies for optimal returns.
Practical Defenses Against Adversarial Machine Learning
Explore real-world attacks on ML systems, from recommendation engines to email filters, and learn practical defense strategies against adversarial machine learning threats.
How Our SREs Safeguard Nanosecond Performance - at Scale - in an Environment Built to Fail
Explore SRE principles in high-frequency trading, balancing innovation with risk management. Learn strategies for safeguarding nanosecond performance in a regulated, failure-prone environment at scale.
Using Rails to Communicate with the New York Stock Exchange
Learn to build scalable trading apps with Rails, managing complex APIs, TCP protocols, and RPC for high-frequency transactions with the New York Stock Exchange.
High-Frequency Trading on Decentralized On-Chain Exchanges
Explore high-frequency trading strategies for decentralized on-chain exchanges, examining their unique challenges and opportunities in the rapidly evolving blockchain ecosystem.
Why Is My App Slow - Defining Reliability in Platform Engineering
Explore statistical approaches for detecting and measuring platform-level latency regressions in serverless environments, focusing on customer-centric performance metrics beyond traditional SLOs.
Low-Latency Trading Systems in C++ - Templated Meta-State Machines in HFT
Explore advanced C++ techniques for optimizing low-latency trading systems using templated meta-state machines in high-frequency trading environments.
C++ Electronic Trading for Cpp Programmers
Explore electronic trading for C++ developers, covering market dynamics, low-latency strategies, and optimized programming techniques for high-frequency trading systems.
Striving for Ultimate Low Latency
Explore techniques for achieving ultra-low latency in C++ programming, focusing on high-frequency trading and market data processing. Learn optimization strategies and pitfalls to avoid.
Algorithmic Trading with Python
Explore systematic trading at Winton Capital Management, focusing on Python's role in data management, signal generation, and order execution for algorithmic trading on global exchanges.
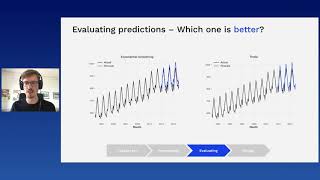
Darts - Unifying Time Series Forecasting Models from ARIMA to Deep Learning
Explore time series forecasting with Darts, a Python library unifying traditional and deep learning models. Learn best practices for preprocessing, backtesting, and achieving quick results in forecasting problems.
Inside the Map Implementation
Explore Go's map implementation, including hash functions, buckets, and performance considerations for efficient data storage and retrieval.
A Performance Analysis of a Trading System over Compilers
Explore high-frequency trading optimization techniques, compiler quirks, and performance analysis in C++. Gain insights on static branch prediction, switch statements, and hardware impacts on trading systems.
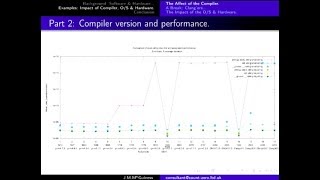
A Performance Analysis of a Trading System over Compliers
Explore micro-optimizations in C++ for high-frequency trading systems, analyzing compiler quirks, branch prediction, and switch statements. Examine performance impacts across different compilers and operating systems.