
Exchanges, Brokers, Dealers, and Clearinghouses in Financial Markets
Explore the evolution of financial markets, from ancient exchanges to modern electronic trading, examining broker-dealer dynamics, order types, and the impact of high-frequency trading on market stability.
Market Microstructure in Practice
Odkryj praktyczne aspekty mikrostruktury rynku i jej wpływ na funkcjonowanie rynków finansowych. Zgłęb kluczowe koncepcje i zastosowania.
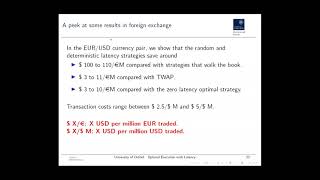
Optimal Execution with Stochastic and Deterministic Delay - SIAM FME Virtual Talk
Explore optimal execution strategies in financial markets with random delays, considering price impact and transaction costs. Learn about innovative impulse control models and their practical applications.
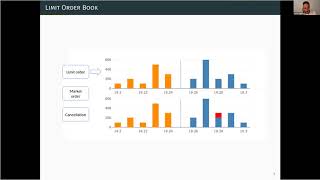
Detecting Spoofing Strategies in High Frequency Trading
Exploring detection methods for spoofing strategies in high-frequency trading, focusing on volume imbalance impact and optimization models to identify manipulative behaviors in limit order books.
How Our SREs Safeguard Nanosecond Performance - at Scale - in an Environment Built to Fail
Explore SRE principles in high-frequency trading, balancing innovation with risk management. Learn strategies for safeguarding nanosecond performance in a regulated, failure-prone environment at scale.
Using Rails to Communicate with the New York Stock Exchange
Learn to build scalable trading apps with Rails, managing complex APIs, TCP protocols, and RPC for high-frequency transactions with the New York Stock Exchange.
High-Frequency Trading on Decentralized On-Chain Exchanges
Explore high-frequency trading strategies for decentralized on-chain exchanges, examining their unique challenges and opportunities in the rapidly evolving blockchain ecosystem.
Low-Latency Trading Systems in C++ - Templated Meta-State Machines in HFT
Explore advanced C++ techniques for optimizing low-latency trading systems using templated meta-state machines in high-frequency trading environments.
C++ Electronic Trading for Cpp Programmers
Explore electronic trading for C++ developers, covering market dynamics, low-latency strategies, and optimized programming techniques for high-frequency trading systems.
Striving for Ultimate Low Latency
Explore techniques for achieving ultra-low latency in C++ programming, focusing on high-frequency trading and market data processing. Learn optimization strategies and pitfalls to avoid.
Inside the Map Implementation
Explore Go's map implementation, including hash functions, buckets, and performance considerations for efficient data storage and retrieval.
A Performance Analysis of a Trading System over Compilers
Explore high-frequency trading optimization techniques, compiler quirks, and performance analysis in C++. Gain insights on static branch prediction, switch statements, and hardware impacts on trading systems.
A Performance Analysis of a Trading System over Compliers
Explore micro-optimizations in C++ for high-frequency trading systems, analyzing compiler quirks, branch prediction, and switch statements. Examine performance impacts across different compilers and operating systems.
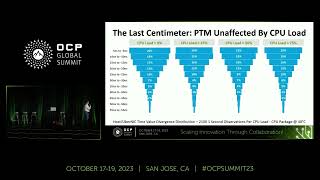
Delivering Immediate Precision Time in Financial Services
Explore precision time synchronization challenges in cloud applications, focusing on PTP/1588 and PCIe PTM implementations for financial services with performance optimization strategies.
A Case Study of Enhancing gRPC Micro-Services for Supporting High Throughput, Low Latency Trading
Explore optimizations for high-throughput, low-latency trading systems using gRPC and Golang. Learn strategies for enhancing performance and deploying improvements in live environments.
How to Simulate a Low Latency Exchange in C++ - Developing Trading Strategies
Develop low latency trading strategies by simulating exchanges in C++. Learn to create simulators for backtesting, evaluating, and optimizing trading models to select profitable strategies.
Polymorphism, Cohesion, and Coupling in C++ - Lecture
Explore low coupling and high cohesion through polymorphism in C++. Learn to implement a performance-efficient framework using template metaprogramming for easy composition and feature addition.