Decision-Based Scenario Clustering - General Bounds for Stochastic Optimization Models
Explore decision-based scenario clustering for stochastic optimization models. Learn to derive efficient bounds and address computational challenges in uncertainty-driven decision-making.
Global Convergence in Stochastic Optimization - ICBS 2024
Explore stochastic optimization algorithms with adaptive variance for non-convex functions, featuring provable convergence rates and numerical examples.
Trade-off Between Optimality and Explainability in Machine Learning Models
Explore the trade-off between model explainability and accuracy in AI/ML, focusing on counterfactual explainability and optimization challenges in high-risk applications.
Set Valued Hamilton-Jacobi-Bellman Equations - Applications and Theory
Explore set valued PDEs and their applications in stochastic optimization, risk measures, and game theory. Learn about dynamic programming principles and set valued HJB equations.
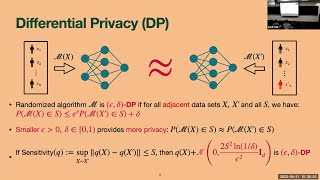
Private Stochastic Optimization with Large Worst-Case Lipschitz Parameter
Explore differentially private stochastic optimization techniques for loss functions with large worst-case Lipschitz parameters, addressing outliers and heavy-tailed data for improved excess risk bounds.

Adversarially Robust Stochastic Multi-Armed Bandits
Explore adversarially robust stochastic multi-armed bandits for optimal experimental design. Learn about algorithms balancing fast and robust learning in real-world applications like digital advertising.
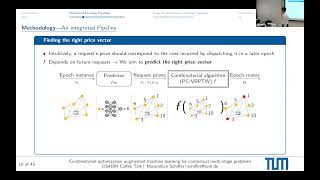
Combinatorial Optimization Augmented Machine Learning for Contextual Multi-Stage Problems
Explore combinatorial optimization augmented machine learning for contextual multi-stage problems, focusing on industrial applications and dynamic stochastic optimization challenges.

Shuffling-based Stochastic Optimization Methods: Bridging the Theory-practice Gap
Explore shuffling-based stochastic optimization methods and their practical applications in bridging theoretical concepts with real-world implementation.
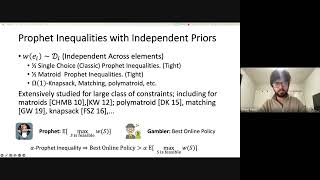
Limitations of Stochastic Selection with Pairwise Independent Priors
Explore stochastic selection problems with pairwise-independent priors and matroid constraints, examining limitations and optimal bounds for contention resolution and prophet inequalities.
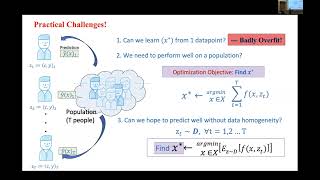
Online Optimization Meets Federated Learning - Tutorial
Explore state-of-the-art theoretical results in online optimization, federated learning, and their intersection. Gain insights into regret analysis, data heterogeneity, and distributed online optimization.