Proximal Gradient Methods for Nonsmooth Nonconvex Minimax - A Unified Convergence Analysis
Explore proximal gradient methods for nonsmooth nonconvex minimax problems, analyzing convergence and complexity through a unified framework for parallel and alternating schemes.
Nonconvex Optimization and the Curse of Local Minima - Lessons Learned from Orbital Tomography
Explore nonconvex optimization algorithms, focusing on quality of fixed points in orbital tomography. Gain insights into evaluating algorithm effectiveness beyond convergence speed.
Optimization of Functions with Low Effective Dimensionality
Explore optimization techniques for functions with low effective dimensionality, focusing on random and deterministic subspace methods for nonconvex problems and efficient subspace learning.
Recent Advances in Optimization Solvers within JuliaSmoothOptimizers
Explore cutting-edge nonlinear optimization solvers in JuliaSmoothOptimizers. Learn about new packages, performance enhancements, and flexible implementations for large-scale problems using high-level linear algebra and automatic differentiation.
Nonconvex Stochastic Programs: Chance Constraints
Explore nonconvex stochastic programs and chance constraints with Jong-Shi Pang, delving into advanced mathematical concepts for optimization under uncertainty.
Nonconvex Stochastic Programs - Deterministic Constraints
Explore nonconvex stochastic programs with deterministic constraints, presented by Jong-Shi Pang from USC. Gain insights into advanced mathematical concepts and their applications.
Quantum Dynamics for Continuous Optimization - Quantum Hamiltonian Descent
Explore quantum Hamiltonian descent algorithms for solving complex optimization problems, focusing on practical applications and implementation through the QHDOPT software package.
Inference and Uncertainty Quantification for Noisy Matrix Completion - Lecture 5
Explore inference and uncertainty quantification for noisy matrix completion, focusing on de-biased estimators and their distributional characterizations for optimal confidence interval construction.
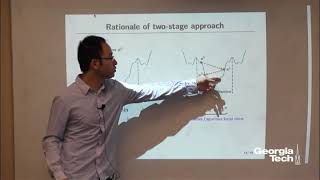
Random Initialization and Implicit Regularization in Nonconvex Statistical Estimation - Lecture 2
Explore nonconvex optimization in statistical estimation, focusing on gradient descent's convergence to optimal solutions without explicit regularization or careful initialization.
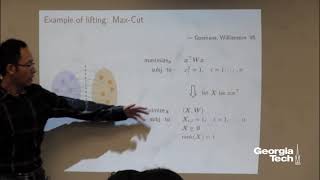
The Power of Nonconvex Optimization in Solving Random Quadratic Systems of Equations - Lecture 1
Explore nonconvex optimization for solving random quadratic systems, achieving optimal accuracy in linear time. Learn about applications in imaging science and neural networks.
Heaviside Composite Optimization and Complementarity Constraints by Progressive Integer Programming
Explore advanced optimization techniques for Heaviside composite functions and complementarity constraints using the progressive integer programming method.
High-Order Moreau Envelope in the Nonconvex Setting: Framework and Algorithms
Explore high-order proximal operators and Moreau envelopes in nonconvex optimization, examining properties, algorithms, and convergence analysis for advanced mathematical applications.

Stochastic Gradient Descent Methods with Biased Estimators
Explore recent advancements in stochastic gradient descent methods, focusing on biased estimators for large-scale optimization and minimax problems in machine learning applications.
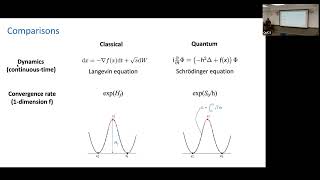
Quantum Speedups for Nonconvex Optimization via Quantum Tunneling Walks
Explore quantum speedups for nonconvex optimization using quantum tunneling walks. Learn how this approach outperforms classical algorithms in specific landscapes with high, thin barriers between minima.