Неермітові моделі ферміонів на ґратці
Дослідіть неермітові моделі ферміонів на ґратці разом з аспірантом Едуардом Найчуком у рамках семінару з теоретичної фізики для поглиблення знань у квантовій механіці.
Python for Finance: Low Risk Investment Options - Part 3
Learn to analyze stocks using Python, covering correlation, risk minimization, ROI calculation, and portfolio optimization techniques for informed investment decisions.
Risk-Aware Reinforcement Learning for Finance
Explore risk-aware reinforcement learning in finance, covering time-consistent approaches and applications to financial modeling. Learn from expert Sebastian Jaimungal about innovative strategies beyond traditional RL methods.
Aspects of Quantum Simulation of the Fermi-Hubbard Model - IPAM at UCLA
Explore quantum simulation of the Fermi-Hubbard model, focusing on Trotter error bounds and optimization techniques for improved accuracy in quantum circuits and time evolution algorithms.
Rethinking Risk
Experts discuss evolving risk management strategies in finance, addressing regulatory impacts, market distortions, and new challenges for investors and banks in a changing economic landscape.
Derivatives Analytics with Python & Numpy
Explore financial derivatives analytics using Python and NumPy, focusing on efficient implementation and practical applications in quantitative finance.
Python for Finance Part 1
Learn to leverage Python for financial analysis, modeling, and algorithmic trading. Explore practical applications in quantitative finance and risk management.

ME3255 - Analyzing NYSE Monte Carlo Model
Analyze NYSE stock data using Monte Carlo simulations. Learn to model market behavior and predict future trends with statistical methods.
Circuit Depth Versus Energy in Topologically Ordered Systems
Delve into circuit depth analysis for quantum many-body systems, exploring energy-depth relationships and geometric constraints in topologically ordered systems through theoretical proofs.
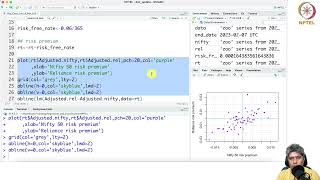
Hands-on Implementation of CAPM Using R
Implement CAPM using R through hands-on practice and practical application.
Percolation Theory
Explore percolation theory, its applications, and fundamental concepts in complex systems and network analysis.

How Will Quantum Computing Affect Our Everyday Lives in the Future?
Explore the potential impact of quantum computing on daily life with Xanadu's CEO and an Economist editor at Collision 2023.

ME3255 - Evaluating a NYSE Monte Carlo Model
Evaluate a NYSE Monte Carlo model using advanced statistical techniques. Gain insights into financial modeling and risk assessment for stock market analysis.
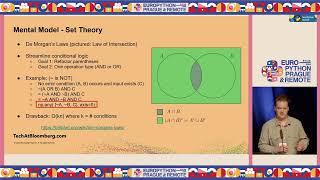
Vectorization Techniques for 1000x Python Speedups - No C or Spark Required
Discover techniques for achieving 1000x speedups in Python through vectorization, matrix operations, and creative optimization strategies. Learn to apply these methods to complex financial and ESG computations.
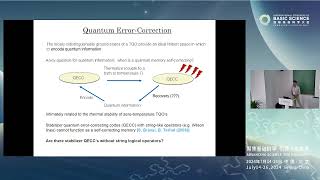
Fracton Quantum Order
Explore fracton phases in quantum systems, their restricted mobility excitations, and ground-space degeneracy. Review key developments and unifying perspectives on these emergent phases.
Introduction to SciPhy Reinforcement Learning - Part 1
Explore SciPhy RL: a neural network-based method for solving stochastic optimal control problems in continuous time, with applications and high-dimensional examples.
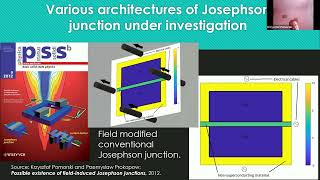
Hybrid Schrödinger-Ginzburg-Landau Approach in Study of Superconducting Integrated Structures
Explore a hybrid Schrödinger-Ginzburg-Landau approach for simulating superconducting lattices and integrated structures. Learn about relaxation algorithms and modeling techniques for superconducting devices.
Critical Phenomena Through the Lens of the Ising Model
Explore critical phenomena through the Ising model with Hugo Duminil-Copin's lecture at IMPA's 70th anniversary conference, featuring insights from a renowned mathematician.
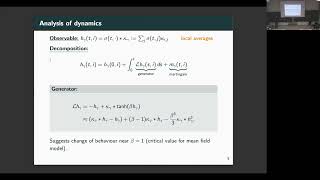
Convergence of the Ising-Kac Model to Φ4 in Three Dimensions
Explore the convergence of the Ising-Kac model to $\Phi^4$ in 3D, analyzing Glauber dynamics and applying regularity structure theory to discrete particle systems.
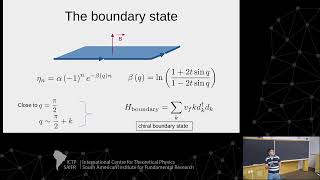
Impurities in the Extended Hofstadter-Hubbard Model
Explore impurities in the extended Hofstadter-Hubbard model, examining their effects on quantum systems and potential applications in condensed matter physics.
Quantum Finance - Lecture 3
Explore advanced quantum finance concepts, focusing on applications in financial modeling and risk assessment using quantum computing techniques.