Basic Calculus for Engineers, Scientists and Economists
Comprehensive overview of calculus fundamentals, covering integration, derivatives, limits, sequences, and functions, tailored for professionals in engineering, science, and economics.

What Is Jacobian - The Right Way of Thinking Derivatives and Integrals
Explore the Jacobian matrix and determinant in multivariable calculus, rethinking derivatives and integrals for a deeper understanding of changing variables in higher dimensions.
Enriching Latent Class Models With Counterfactual Prediction - Mark Gilthorpe
Exploring counterfactual prediction in AI: enhancing prediction algorithms with 'what if' capabilities for improved decision-making and fairness in healthcare, insurance, and beyond.
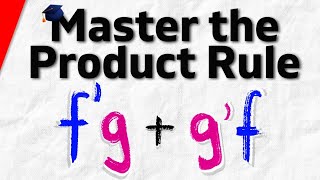
Master the Product Rule - Calculus 1 Exercises
Comprehensive tutorial on mastering the product rule in calculus, featuring 20 practice problems of increasing difficulty covering various mathematical concepts and applications.
Wall Crossing for Moduli of Stable Pairs
Explore wall crossing phenomena in moduli spaces of stable pairs, examining their geometric and algebraic properties and implications for birational geometry.
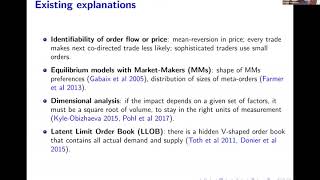
A Simple Microstructural Explanation of the Concavity of Price Impact
Explore a microstructural model explaining price impact concavity in financial markets, with insights on order flow, fundamental pricing, and meta-order execution dynamics.
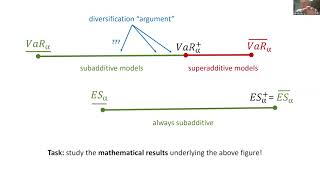
Dependence, Uncertainty, and Risk - Prof. Paul Embrechts
Explore quantitative risk management through extremal bounds for risk measures, focusing on uncertainty in interdependence between risk factors and its impact on portfolio analysis.
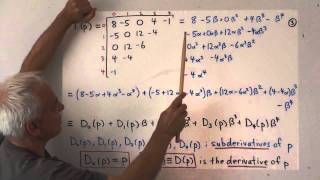
Calculus with Integral Polynumbers - Arithmetic and Geometry Math Foundations 70
Explore calculus with integral polynumbers, covering Pascal's Array, Taylor polynumbers, derivatives, and subderivatives. Learn alternative approaches to traditional calculus concepts and their applications.
Complex Monge-Ampère Operators and Functional Hermitian Intrinsic Volumes
Explore geometric construction of Monge-Ampère operators on finite convex functions, examining their properties and related valuations as functional versions of Hermitian intrinsic volumes.

Unlocking Your Freedom - Exploring the Boundaries and Possibilities of Math in Finance
Explore the innovative applications of mathematics in finance, unlocking new possibilities and expanding boundaries for financial analysis and decision-making.
Dimer Models and Random Tilings - Part 1
Explore dimer models and random tilings with Cédric Boutillier. Learn about Kasteleyn's theory, combinatorial correspondences, and asymptotic methods for studying perfect matchings on lattices.
Recent Advances in Valuations on Function Spaces
Explore recent developments in valuations on function spaces, focusing on convex and continuous functions, with insights into measure-valued valuations and their classifications.

Path Convergence of Markov Chains on Large Graphs
Explore path convergence of Markov chains on large graphs, examining theoretical aspects and applications in network science, probability theory, and complex systems analysis.
Spin Systems on Spatial Random Graphs
Explore spin systems on spatial random graphs, examining their properties, dynamics, and applications in network science and statistical physics.
Asymptotics of Invariant Measures of Mean-field Markov Models on Countable State Spaces
Explore asymptotics of invariant measures in mean-field Markov models on countable spaces. Gain insights into network science, probability theory, and applications in complex systems and data analysis.
Wall-Crossing for Elliptic Central Charges
Explore generating series of K-theoretic enumerative invariants and their relation to stability conditions in GIT quotients, focusing on elliptic central charges and wall-crossing phenomena.
Chance to See Life - Expressing the World Through Probability
Exploring mathematical models and probability to interpret the world, blending quantitative analysis with human nature insights for a unique perspective on life and investment.
Deep Solver for Jumps in Backward Stochastic Differential Equations - Lecture
Innovative extension of deep solver for FBSDEs with jumps, using neural networks to tackle high-dimensional problems in option pricing and counterparty credit risk.
Weighted Blowups, Wall-Crossing and Weak Factorization
Explore stack-theoretic weighted blowups and their applications in resolution of singularities, destackification, wall-crossings, and weak factorization for more natural and efficient algorithms.
Path-Dependent PDEs and Mean Field Control - SIAM FME Virtual Talk Series
Explore advanced mathematical concepts in finance: path-dependent PDEs, rough volatility, and mean field control. Gain insights from experts on convergence rates and numerical analysis in financial modeling.
The Hermitian Trace Code - Advances in Error-Correcting Codes
Explores character sum bias over high genus curves, strengthening Stepanov-Bombieri approach. Analyzes multiplicity in function fields using new 'universal derivative-fix' lemma.