
Risk and Financial Crises - Probability Theory in Financial Markets
Explore probability theory in financial crises context, covering expected value, variance, covariance, and regression analysis. Learn about risk decomposition and the limitations of normal distribution assumptions in finance.
Probability and Stochastics for Finance
This course provides the minimum mathematical requirements to study mathematical finance or more precisely the pricing of financial derivatives.
Basic Limit Theorems
Explore fundamental limit theorems in probability and statistics, including convergence modes, central limit theorem, and law of large numbers, with practical examples and proofs.

Central Limit Theorem - Sampling Distribution of Sample Means - Stats & Probability
Comprehensive exploration of the Central Limit Theorem, covering sampling distributions, statistical concepts, and probability problems with practical examples and various distribution types.
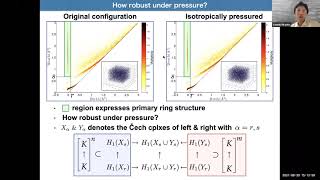
On Characterizing Rare Events in Persistent Homology
Explore rare events in persistent homology, focusing on indecomposables in multi-parameter settings. Learn about large deviation principles and laws of large numbers in topological data analysis.
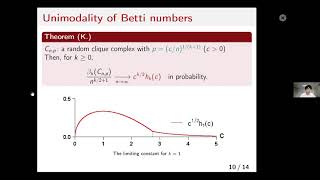
A Limit Theorem for Betti Numbers of Random Simplicial Complexes
Explore asymptotic behavior of Betti numbers in homogeneous and spatially independent random simplicial complexes, extending previous work on Linial-Meshulam complexes using local weak convergence.
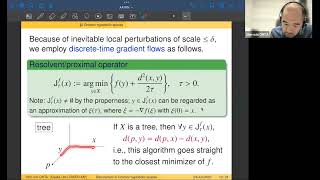
Barycenters and a Law of Large Numbers in Gromov Hyperbolic Spaces
Explore barycenters in Gromov hyperbolic spaces, examining contraction properties and a law of large numbers for convex optimization applications in metric spaces.

Probability Distribution Formulas
Explore formulas for binomial, geometric, Poisson, uniform, and exponential probability distributions. Master key concepts to solve statistical problems effectively.
Generalization Error and Stability
Explore statistical learning theory, focusing on generalization error, stability, and empirical risk minimization. Gain insights into universal consistency and the law of large numbers.